Who commercial solar is for
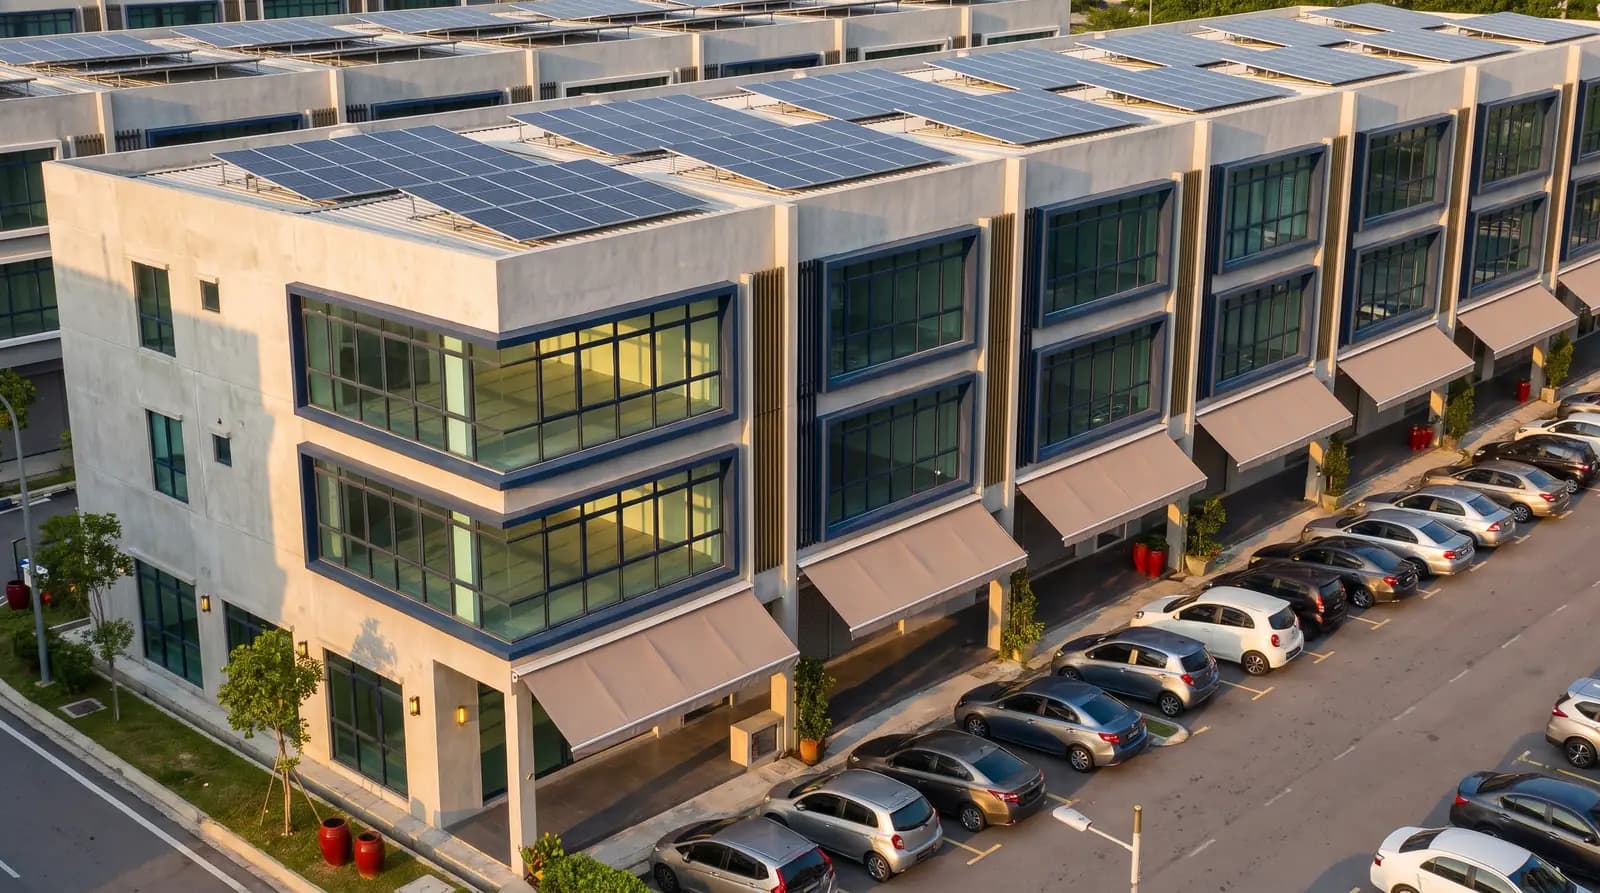
This page is written for the person who signs off on a TNB bill for a business property — a facility manager, finance director or owner of an office, hotel, retail unit, shop-lot or warehouse. If your building runs on a domestic tariff, the residential process applies instead; if it runs on an industrial tariff (manufacturing, a plant with shift patterns, or a maximum-demand charge that dominates the bill), the industrial and factory pages below are the better starting point.
The common thread across office, hotel, retail and warehouse buildings is that the electricity bill is driven almost entirely by the energy charge — how many kWh you consume — rather than by a maximum-demand charge. That's what makes the sizing and savings method on this page different from the industrial pages, and it's covered in the next two sections.
- Not the right page? A manufacturing plant on an industrial tariff: Industrial solar. One operating factory rooftop: factory & industrial solar. No usable roof or car park at all: CRESS green electricity through the grid.
Commercial solar installation in Malaysia: what Trexon delivers
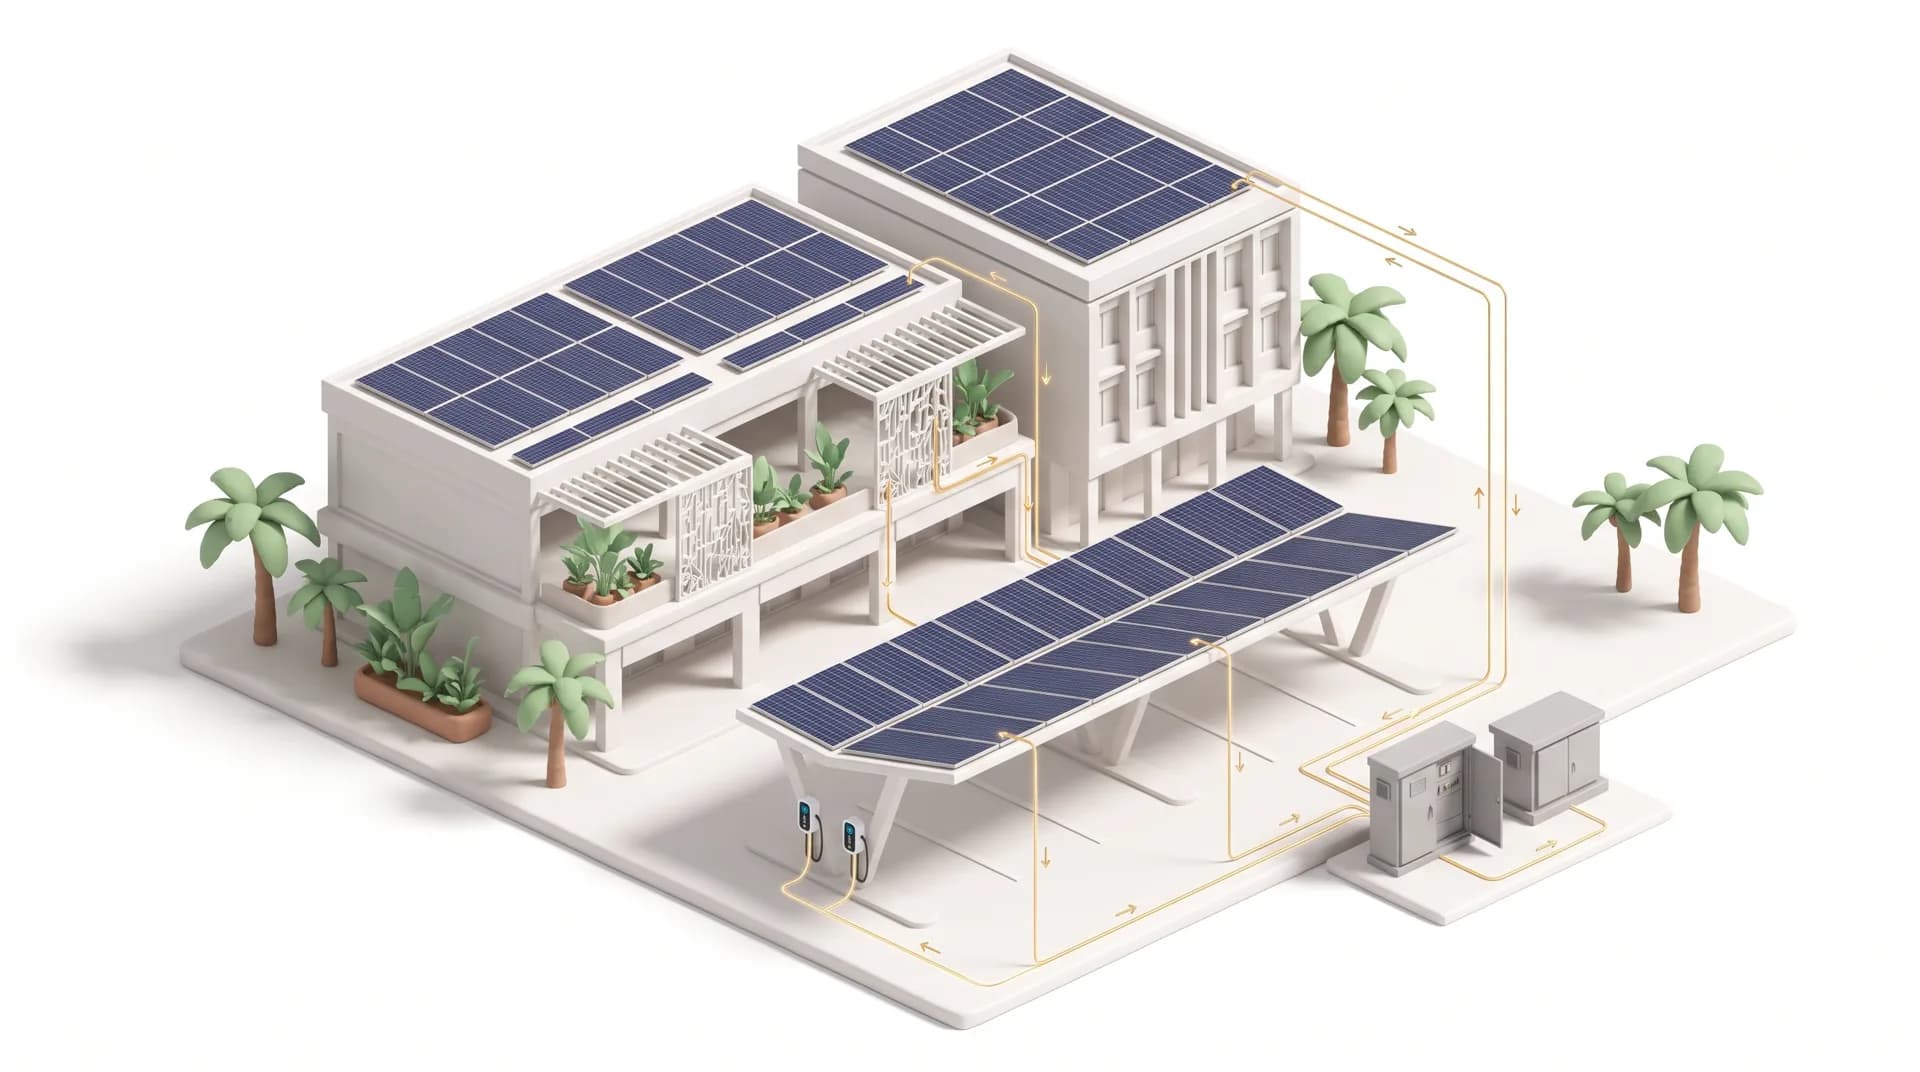
Trexon delivers commercial solar installation as one engineering, procurement and construction (EPC) contract: the same team designs the system, buys the equipment, installs it and takes it through the regulatory steps, so the business deals with one counterparty from the first bill review to handover. The scope is the same for an office, hotel, shop-lot, retail unit or warehouse — only the sizing and the roof mounting change. This is what solar for business looks like in practice, and it is the same C&I solar process set out on the C&I solar overview, applied to commercial premises.
| Stage | What Trexon does | What you provide |
|---|---|---|
| Design | Sizes the system against your TNB bills, maximum demand and usable roof or car-park area, and prepares the layout and single-line diagram | Bills, roof plan and the existing single-line diagram |
| Solar ATAP filing | Prepares and files the Solar ATAP application with SEDA as your registered PV service provider, and arranges any connection assessment study TNB requires for larger systems | Company documents and the account holder's authorisation |
| Procurement and installation | Supplies Jinko N-type modules with Solis, Huawei, Sungrow or GoodWe inverters, mounting and switchgear, and installs to the agreed scope | Site access and a shutdown window for the tie-in |
| TNB commissioning | Coordinates testing and the bi-directional meter installation with TNB before the export credit starts | Attendance at the commissioning visit |
| Monitoring and handover | Sets up inverter monitoring so you can see generation, and hands over as-built drawings, warranties and commissioning records | Internet access at the inverter location |
How does GITA work for solar in Malaysia in 2026?
Current rules, until 31 December 2026. A company that owns a solar system for its own use can claim GITA Asset at Tier 2: an allowance of 60% of qualifying capital expenditure, set against up to 70% of statutory income. Under the current MGTC guideline the capex must be incurred, the system commissioned and the GITA Asset application received by MGTC by 31 December 2026 — the application can only be filed after commissioning. A system the company does not own does not qualify, because the claimant must own the asset.
From 1 January 2027 — proposed under Budget 2027, subject to legislation. The Budget 2027 tax measures propose extending GITA Asset to purchases verified by MGTC up to 31 December 2030, with two changes that matter for solar: a standalone solar system is no longer listed, and solar integrated with battery storage (BESS or ESS) moves to Tier 1 at 100% of qualifying capital expenditure, still set against up to 70% of statutory income. Companies would have to apply to MGTC within 24 months of purchase. These are announced proposals, not yet gazetted, and MGTC has not published its updated guideline or asset list. How a 2026 purchase verified in 2027 will be treated has not been published either, so plan to commission and apply in 2026. Source: MOF Budget 2027 Tax Measures, Appendix 25.
For a commercial building, a solar-only project that misses 31 December 2026 would no longer qualify under the proposal, while a solar + battery design may qualify at the higher rate from 2027. See GITA for commercial solar 2026.
How TNB charges a commercial account
Low-voltage commercial accounts on the Non-Domestic Low Voltage tariff (formerly Tariff B) pay a combined marginal rate of RM0.5068/kWh, made up of energy, capacity and network charges, plus a RM20 monthly retail charge and a 1.6% KWTBB renewable-energy fund levy on the bill. That schedule is stamped 2025-07-01 — see TNB Commercial & Industrial Pricing & Tariffs for the current published rates, and note that the Automatic Fuel Adjustment (AFA), which replaced the ICPT in July 2025 and is set monthly, changes the bill regardless of the base schedule.
Larger buildings on medium-voltage tariffs — Medium Voltage General or Medium Voltage Time of Use — carry an additional maximum-demand (MD) charge, billed per kW against the single highest half-hourly demand recorded in the billing month, on top of the energy and network components. MV Time of Use also splits the energy rate into a peak period (14:00–22:00, Monday to Friday) and a cheaper off-peak rate for all other hours. We don't publish medium-voltage RM/kW figures on this page, because that schedule resets on its own cycle — read the exact rate off the "Maximum Demand" line of your own TNB bill, or bring the bill to your first assessment and we'll read it with you.
How much can rooftop solar save an office, hotel, retail or warehouse business?
The honest answer is a formula, not a fixed percentage: monthly saving equals the kilowatt-hours your solar system generates and you consume on site, multiplied by your marginal Non-Domestic Low Voltage (or medium-voltage energy) rate. There is no single number that applies to every building, because the variable that actually moves the outcome is how much of your daytime load overlaps with the solar generation curve — not the size of the system alone.
An office that empties out by 6pm and sits idle on weekends will self-consume a smaller share of a large system than a warehouse running pick-and-pack shifts five or six days a week. The load-pattern section below sets out typical self-consumption ranges by building type, and the worked example directly below shows the full calculation for one case, step by step, so you can see exactly where the number comes from.
How much does commercial solar cost in Malaysia?
Cost is priced per project, not per watt. Commercial rooftop systems are priced per project from your 12 months of TNB bills, roof plan and single-line diagram, plus a photo of the meter and main switchboard; batteries, structural work and MV switchgear are quoted separately. The booking (20% of the system price, capped at RM20,000) locks in your slot and engineering review and is credited in full against the project. See commercial solar panel cost Malaysia for what drives price.
Is a multi-tenant commercial building eligible for Solar ATAP?
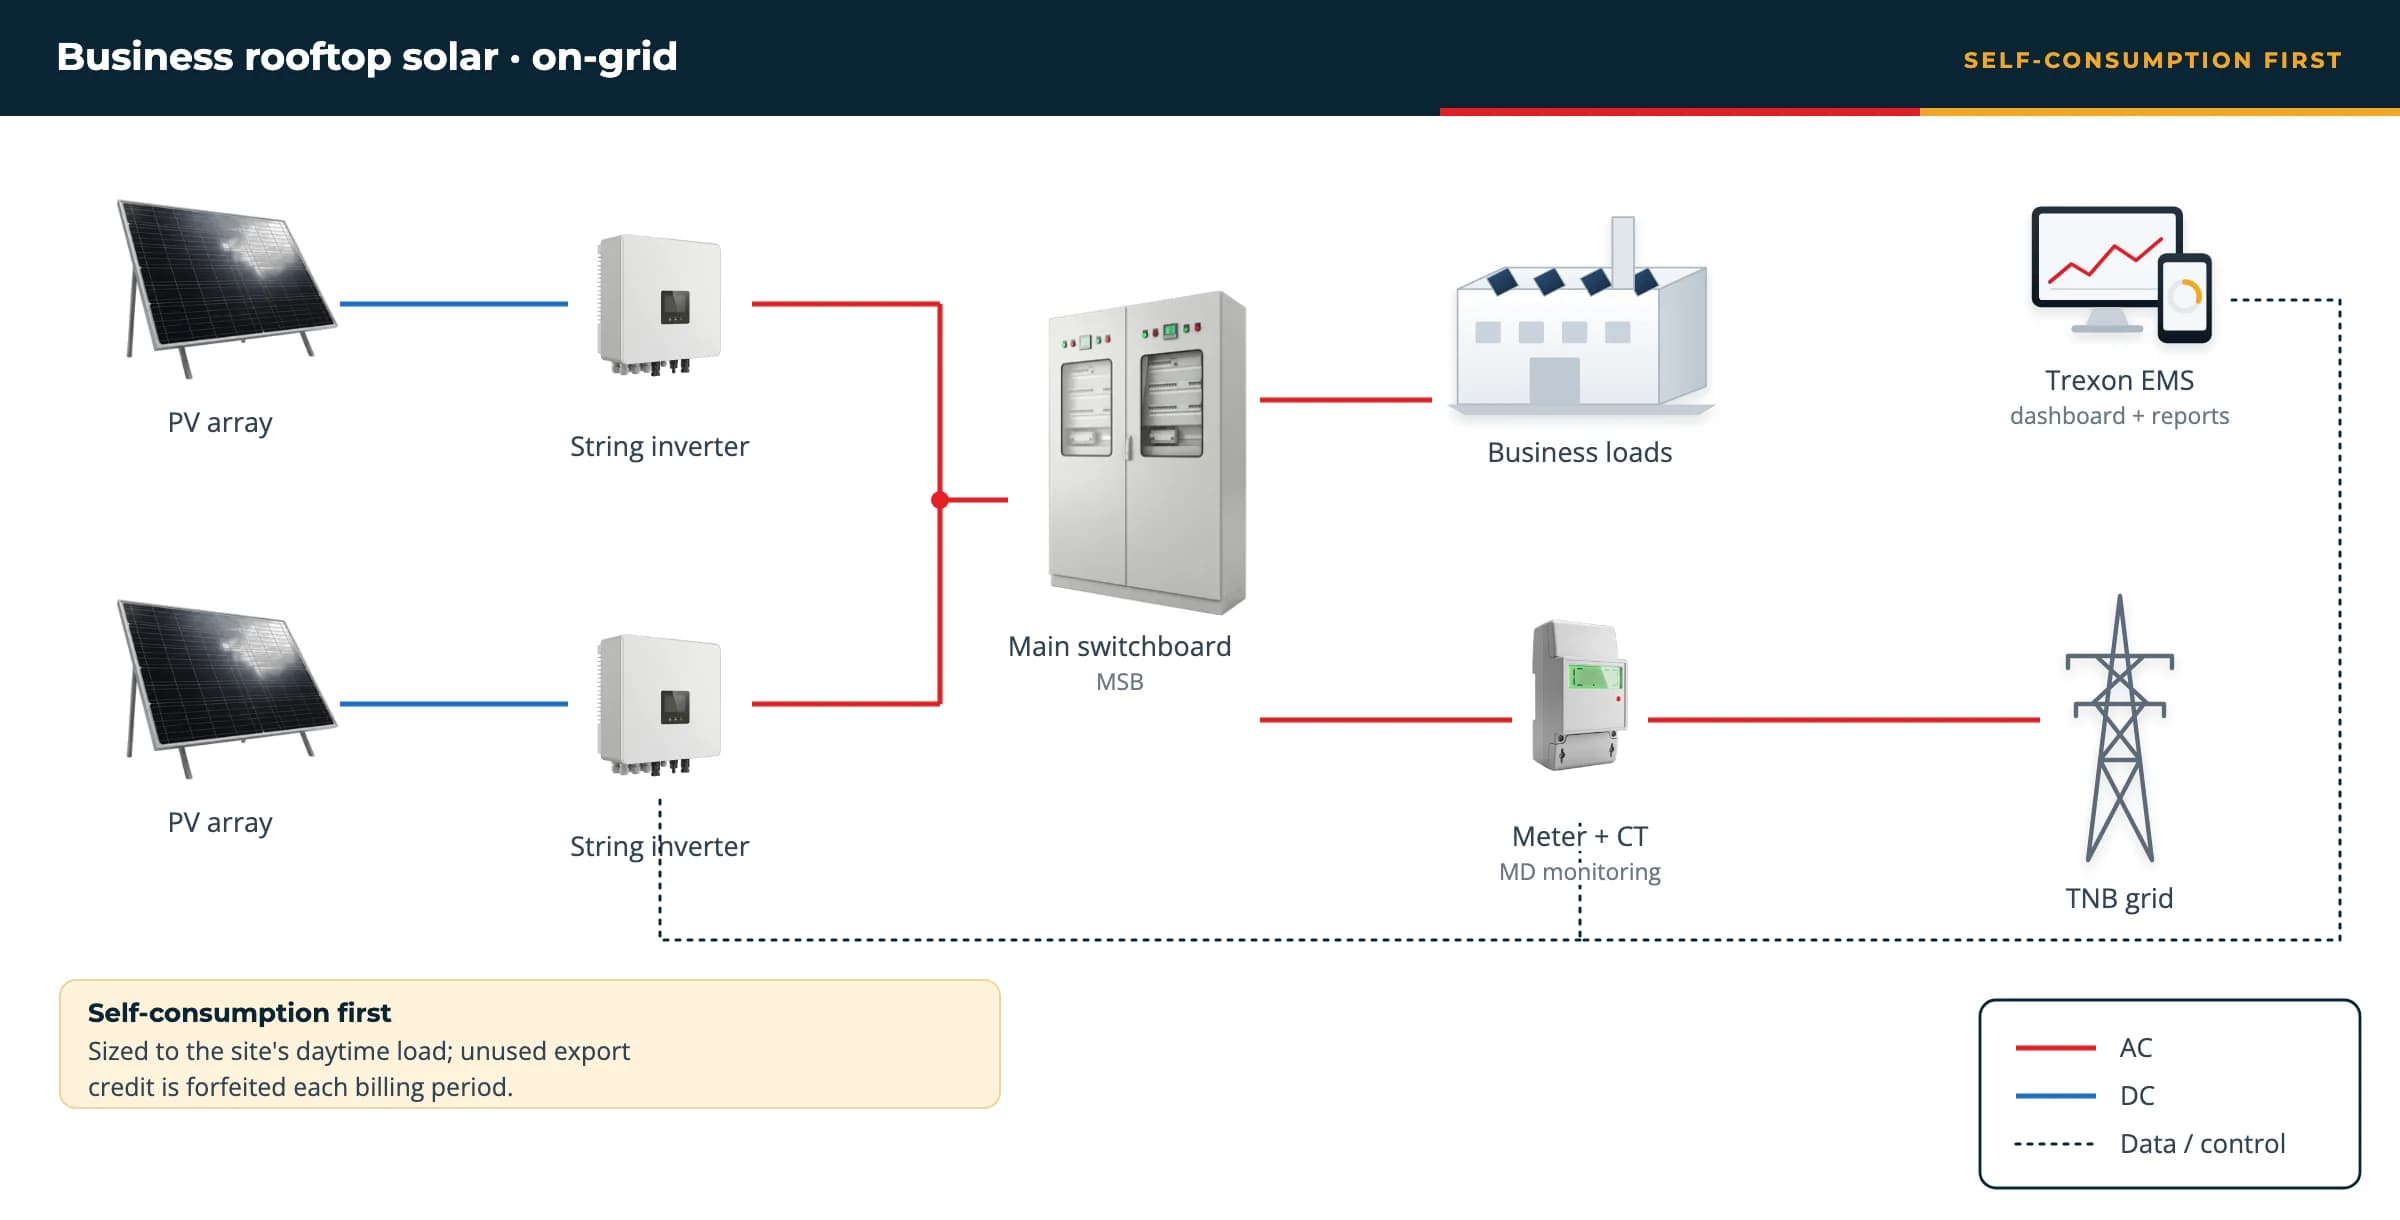
No. Section 6.1(d) of the Solar ATAP guidelines excludes multi-tenant premises. Single-occupier buildings with their own TNB account can join for a 10-year term; exports are credited at the TNB's monthly average wholesale electricity price (not the retail energy charge) and unused credit is forfeited each month. Multi-tenant owners can still install self-consumption systems sized to common-area load — see strata and JMB solar.
Sizing a commercial system: method and worked example
Sizing starts from whichever constraint binds first: your maximum demand, or your available roof and car-park area. Under Solar ATAP (GP/ST/No. 60/2025 §8.3), a non-domestic system's inverter output is capped at 100% of your maximum demand in kWac (the average of the past 12 months' recorded MD), subject to TNB's network assessment (§8.4) and a hard ceiling of 1,000 kWac per installation (§8.5) — DC-oversized, battery-buffered designs are permitted provided the inverter's AC output still fits inside that cap. In practice, most office, hotel and retail buildings are area-constrained long before they reach the MD cap. Multi-tenant premises are not eligible for Solar ATAP (§6.1(d) of the guidelines); single-occupier premises with their own TNB account can apply.
The generation estimate itself uses Trexon's standard yield basis: 105.0 kWh of monthly generation per installed kWp (30 days × 3.5 peak-sun-hours, the same basis as Trexon's savings engine and industrial-park pages; your proposal uses your site's own orientation and shading). The worked example below applies that assumption to a single illustrative case. Trexon designs around Jinko 620W N-type modules with Solis, Huawei, Sungrow or GoodWe string or hybrid inverters, selected per site.
Worked example: 60 kWp office building on the Non-Domestic Low Voltage tariff
Illustrative example — labelled assumptions, not a quotation
- System size (assumed)
- 60 kWp
- Source: Illustrative — chosen for this example only
- Tariff
- Non-Domestic Low Voltage, RM0.5068/kWh
- Source: TNB Non-Domestic Low Voltage schedule, stamped 2025-07-01
- Generation assumption
- 105.0 kWh per kWp per month
- Source: Trexon yield basis (30 days × 3.5 peak-sun-hours)
- Self-consumption (office, no battery)
- 95%
- Source: Model assumption at ~30% solar penetration, no battery
- Monthly generation: 60 kWp × 105.0 kWh per kWp = 6,300 kWh
- Self-consumed energy: 6,300 kWh × 95% = 5,985 kWh
- Monthly saving: 5,985 kWh × RM0.5068/kWh = RM3,033
- Annual saving: Monthly saving × 12 = RM36,398
- Simple payback: Your quoted installed cost ÷ annual saving = quoted cost ÷ RM36,398 per year
This example excludes the retail service charge, the KWTBB levy and any export credit for surplus generation, and assumes the system fits inside the Solar ATAP capacity cap for this site's maximum demand. It is not a quotation — every real project brief is sized against your own bill and roof survey.
Roof types we install on
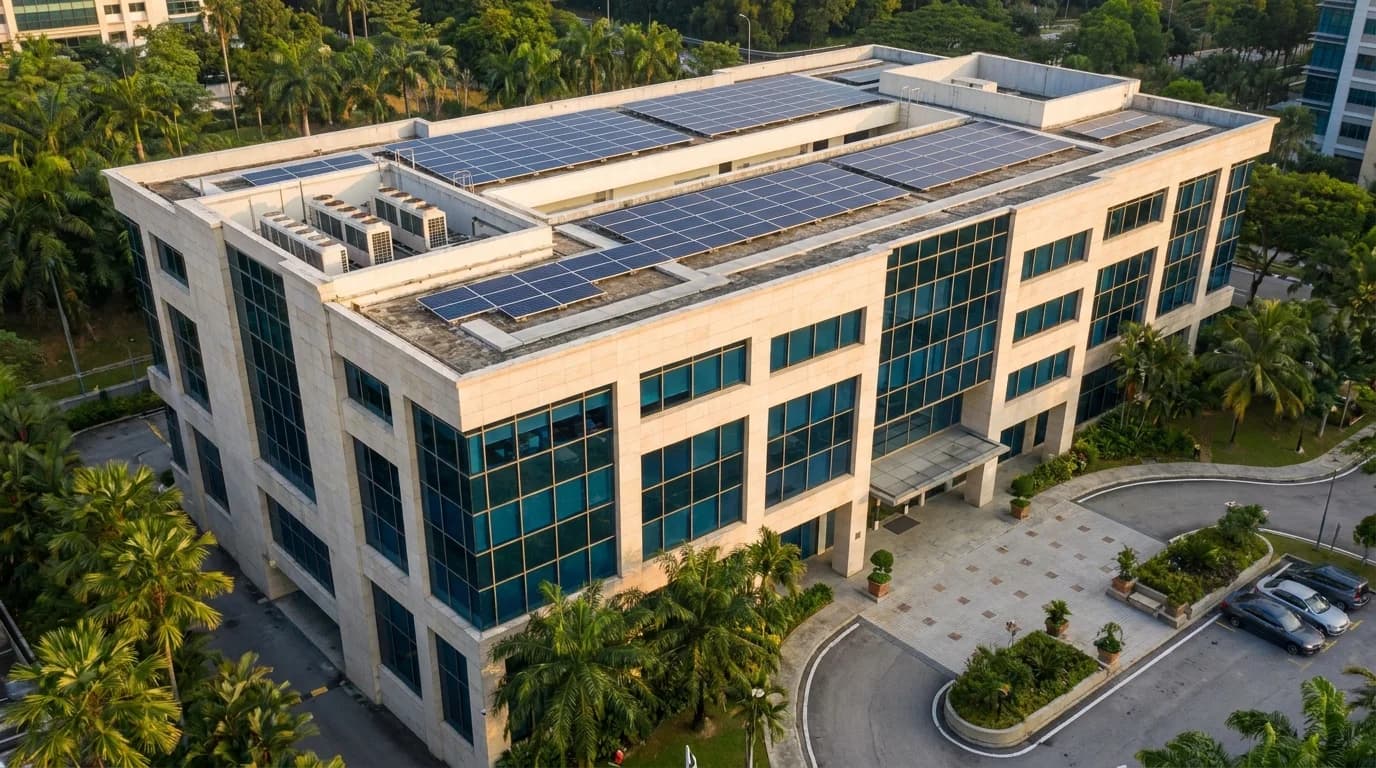
The roof decides the mounting, the structural check and most of the installation risk. Commercial buildings in Malaysia usually have one of four roof types, and each is handled differently. Under the Solar ATAP guidelines the mounting structure must comply with the Registration of Engineers Act 1967, so every design is checked against the roof it sits on before installation starts.
| Roof type | Mounting | Structural check | Typical issue |
|---|---|---|---|
| Metal deck (trapezoidal, through-fastened) | Rails fixed to the roof sheet or purlins with sealed fasteners | Purlin spacing and condition, wind uplift | Sealing every penetration, and replacing corroded sheets before the array goes on |
| Klip-Lok or standing seam (concealed fix) | Non-penetrating clamps on the seams or ribs | Rib profile, clip capacity and wind uplift | Using a clamp rated for the exact profile — no drilling through the sheet |
| Reinforced-concrete (RC) flat slab | Ballasted or anchored tilt frames | Slab capacity for the ballast load, parapets and drainage falls | Keeping the waterproofing intact and leaving access to HVAC plant |
| Membrane-covered flat roof | Ballasted frames on protection pads | Load capacity and membrane condition | Coordinating with the waterproofing contractor so its warranty is not voided |
Why your load pattern decides self-consumption — and what happens to weekend surplus
Self-consumption is not a fixed property of solar — it's a property of when your building uses electricity. Trexon's modelling assumes an office self-consumes about 95% of a correctly-sized system's output (weekday, daytime-heavy load), a warehouse about 92%, a shopping or retail premises about 80%, and a 24/7 hotel — where a large share of demand shifts to evenings and early mornings — about 75%, all at roughly 30% solar penetration with no battery. These are model assumptions for sizing, not a promise for any specific building.
The uncovered share of generation — a closed office on a Sunday, for instance — doesn't simply vanish. Under Solar ATAP, surplus is exported to the grid and credited at the TNB's monthly average wholesale electricity price (not the retail energy charge), under a 10-year contract, and unused credit is forfeited at the end of each month rather than rolled over. What matters at the sizing stage is that a building with a large weekend or evening gap between load and generation should be sized to its weekday self-consumption, not to its roof area alone — oversizing past that point buys export credit, not full-value savings.
Solar ATAP vs SELCO for a business
A business on a TNB supply in Peninsular Malaysia has two routes. Solar ATAP connects the system behind TNB's bi-directional meter and credits any surplus; SELCO (self-consumption) keeps every kWh on site and exports nothing. For most commercial buildings Solar ATAP is the default, because weekend and public-holiday surplus earns a credit instead of being curtailed. SELCO suits a building whose daytime load always exceeds what the roof can generate.
| Point | Solar ATAP | SELCO (self-consumption) |
|---|---|---|
| Surplus export | Credited at TNB's monthly average wholesale electricity price; unused credit is forfeited each month | Not allowed — the system must limit its output so nothing flows to the grid |
| Contract term | 10-year Solar ATAP contract, after which the system continues as self-consumption | No export contract |
| Capacity limit | Inverter output up to 100% of maximum demand, capped at 1,000 kW per installation | No Solar ATAP cap; sized to on-site load with export limiting, subject to TNB technical requirements |
| Best for | Offices, retail and warehouses with weekend or holiday surplus | Buildings whose daytime load always exceeds generation, or premises that cannot join Solar ATAP |
Solar ATAP terms: GP/ST/No. 60/2025 §8 and §14. Multi-tenant premises cannot join Solar ATAP (§6.1(d)).
Own, borrow, instalment or hire purchase: how to structure the purchase
There are four ways a Malaysian business can fund a commercial solar project with Trexon, and the choice affects who claims the tax incentives in the tax incentives section and how the cash flow lands against your existing bill. In every route the business owns the system: Trexon does not offer arrangements where a third party owns the equipment on your roof.
Cash or hire purchase. For a business that would rather not pay in one go, Trexon offers a 2 to 5 years hire-purchase plan through Mitsubishi HC Capital Malaysia Sdn Bhd. Published rates are 3.6–3.95% flat p.a., which is an effective rate of about 6.8–7.4% a year once the flat basis is converted — compare that effective figure, not the flat one, with a bank loan. The lender sets the final rate and any deposit at credit approval. Because the customer owns the system at the end of the term, the customer — not the financier — claims capital allowance and GITA. Hire purchase is for commercial and industrial customers only.
| Route | Who owns it | Upfront cost | Who claims GITA / capital allowance | Best for |
|---|---|---|---|---|
| Outright purchase | You (the customer) | Full cost at commissioning | You | Businesses with capital available who want the full lifetime saving |
| Green or bank loan | You (the customer) | Financed through a bank facility — any down payment depends on the bank | You | Businesses preserving cash while still owning the asset outright |
| 0% card instalment plan (IPP) | You (the customer) | Paid over up to 24 months on a participating bank card | You | Smaller systems where the business wants to own the asset without a bank loan |
| Hire purchase (2-5 years) | You (the customer), outright once the term completes | Financed through Mitsubishi HC Capital at 3.6–3.95% flat p.a. (effective about 6.8–7.4% a year); any deposit is set at credit approval | You — because you end up owning the asset | Businesses that want the asset on their own balance sheet but would rather not pay for it in one go — see hire purchase |
Trexon's 0% card instalment plan runs up to 24 months maximum — see commercial financing routes for how each option is structured in practice.
Tax incentives for commercial solar
Solar PV installed for your own consumption can qualify for a Green Investment Tax Allowance (GITA) Asset claim at Tier 2, subject to MGTC verification — an allowance equal to 60% of qualifying capital expenditure, which can be offset against up to 70% of your company's statutory income in a given year of assessment, under a window that currently runs to 31 December 2026. The system must be commissioned and the MGTC application submitted by 31 December 2026. See the GITA tax incentive guide for the full claim process.
Where GITA isn't claimed or doesn't fully apply, solar equipment can also qualify as plant and machinery under standard capital allowance rules — a 20% initial allowance in the first year of assessment plus a 14% annual allowance, both of which reduce the income on which corporate tax (24% for non-SME companies) is charged. See capital allowance for solar panels in Malaysia for the mechanics and worked figures.
Indicative only. Subject to MGTC verification, applicable tax law and confirmation by the customer’s licensed tax adviser. The system must be commissioned and the GITA Asset application submitted to MGTC by 31 December 2026.
Solar + battery for business: lower evening and MD charges, and GITA from 2027
Solar alone cuts the energy part of the bill in daylight. A battery adds two things solar cannot: it moves midday surplus into the evening, and it can trim the half-hourly peak that sets a medium-voltage account's maximum-demand (MD) charge. Whether that pays depends on the tariff. A Non-Domestic Low Voltage account has no MD charge, so there a battery is mainly about evening load and surplus that would otherwise be exported at the lower credit rate. A building on Medium Voltage General or Time of Use — a large hotel, a mall, a cold-store warehouse — can also cut MD, and on ToU can discharge into the 14:00–22:00 weekday peak.
Sizing uses half-hourly load data, not just the monthly bill: the inverter becomes a hybrid unit, the battery is sized to the evening gap or the MD peak you want to cut, and the array is sized as before. Trexon specifies GoodWe and Solis hybrid inverters with matching battery storage, selected per site, and models every design on your own load data before it is quoted.
Tax is the other reason to look at storage now. Under the Budget 2027 proposal, solar integrated with BESS or ESS would move to GITA Asset Tier 1 at 100% of qualifying capital expenditure for purchases verified from 1 January 2027, while standalone solar would drop out — announced, subject to legislation, as set out in the GITA section above. See commercial battery storage and maximum demand peak shaving.
From project brief to commissioning: what happens after you apply
The process runs in a fixed sequence, without a promised turnaround time — every step depends on your documentation, site access and, for larger systems, TNB's own processing.
- You send the project brief below with your bill, tariff category and operating pattern.
- Trexon's commercial team reviews the bill and load information remotely and comes back with a scoped proposal.
- Reserve the project with a booking of 20% of the system price, capped at RM20,000, credited in full to the system price; an engineer then verifies roof, switchboard and access on site, and we confirm whether commissioning and the MGTC submission by 31 December 2026 are achievable for your site before you pay anything further.
- The system is engineered to your confirmed load and roof survey, and the Solar ATAP application is filed with SEDA on your behalf.
- Equipment is procured and the system is installed to the agreed scope.
- TNB commissions and tests the interconnection before the export credit arrangement goes live.
- You receive the full project handover pack — as-built drawings, warranties and commissioning documentation.
What documents does an installer need to quote a commercial solar project?
Four documents let an engineer size and price a commercial system without guessing. Send them with the project brief below; anything missing is collected during the review.
| Document | What it tells the engineer |
|---|---|
| 12 months of TNB bills (minimum 6) | Tariff category, monthly kWh and maximum demand |
| Roof plan or layout | Usable area, roof material and structure |
| Single-line diagram (SLD) | Connection point, breaker capacity and switchgear work |
| Photo of the TNB meter and main switchboard | Meter type and the space available for the tie-in |