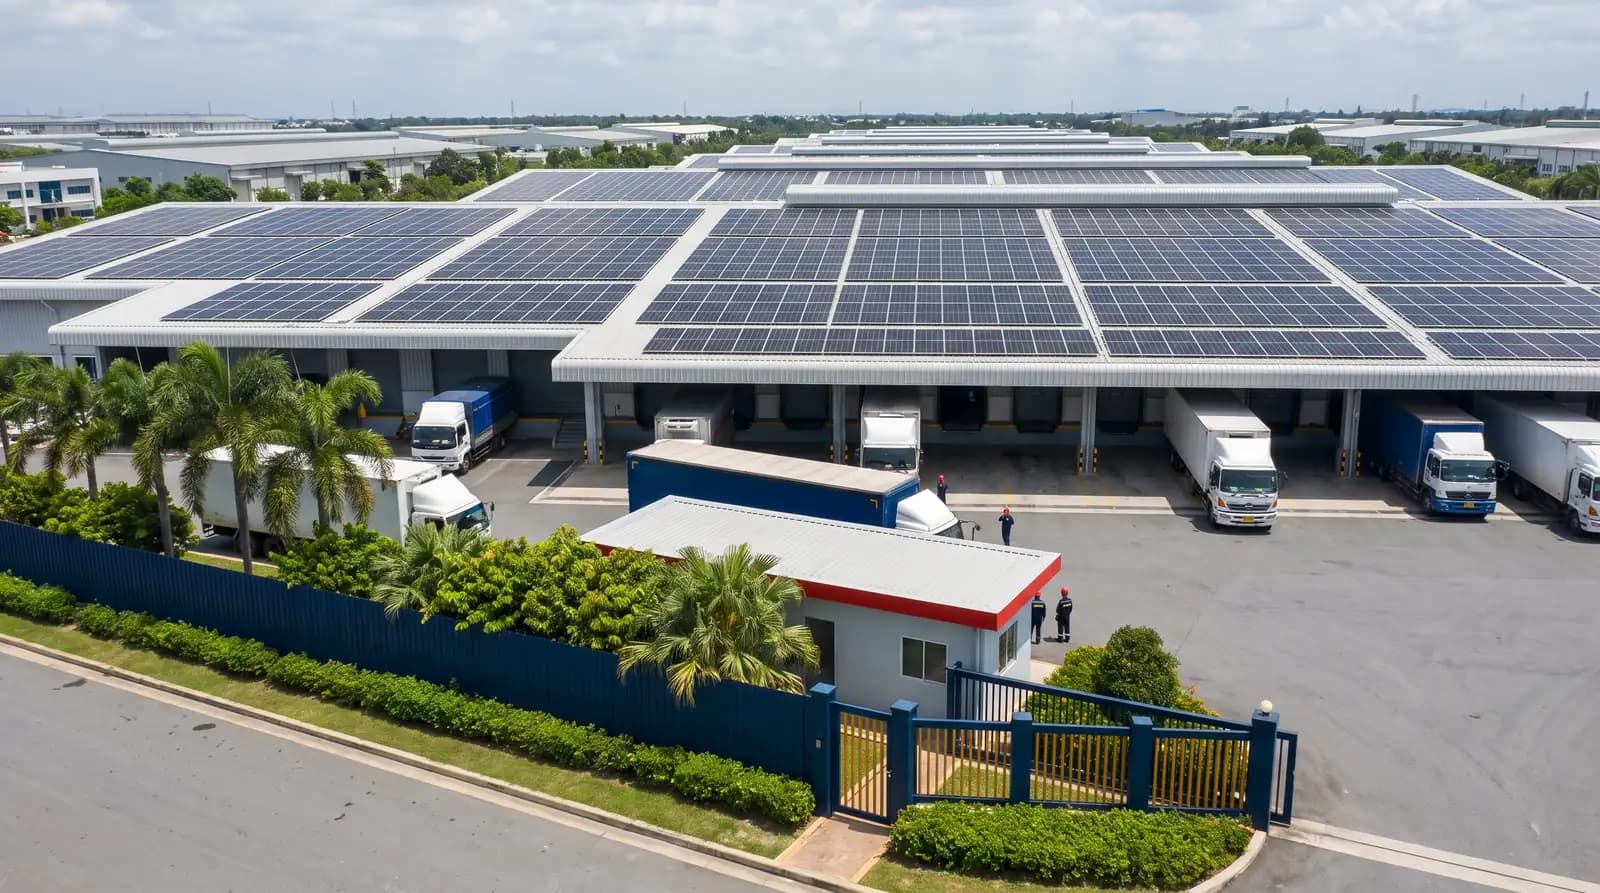
GITA: The 60% Solar Tax Incentive Every Malaysian Company Should Claim Before Dec 31, 2026
GITA Application Window Closes 31 December 2026
Qualifying capital expenditure must be incurred and the MGTC application submitted by this date. The application can only go in after commissioning, so the system must be installed and commissioned before then. Installation typically takes six to ten weeks.
What Is GITA? (30-Second Summary)
- GITA = Green Investment Tax Allowance. A Malaysian corporate tax incentive for companies that invest in qualifying green technology assets.
- For solar PV own consumption: 60% allowance on qualifying capital expenditure, set off against up to 70% of statutory income per year.
- Administered by MGTC (not MIDA) for solar own-consumption applications since January 2024.
- Deadline: 31 December 2026. Capex must be incurred and application submitted to MGTC within this window.
- Who qualifies: Malaysian-incorporated Sdn Bhd / Bhd companies that own and install solar for their own electricity consumption.
Every year, Malaysian manufacturers and commercial building owners pay millions in corporate tax that they could legally reduce — simply by investing in a rooftop solar system and claiming the Green Investment Tax Allowance (GITA). Many business owners are not aware of it, so ask your tax agent whether it applies. And the window closes on 31 December 2026.
This guide covers exactly what GITA is, the verified 2026 rates and rules, a worked example for a real factory-scale system, how it differs from GITE and from normal capital allowances, and the step-by-step application process. All facts are sourced from the official MGTC Green Technology Tax Incentive Guidelines (April 2024).
If you are planning solar for factory roofs or a commercial solar installation for an office or retail building, GITA is the allowance that shortens the payback.
1. What Is GITA? (Full Explanation)
GITA stands for Green Investment Tax Allowance. It is a tax incentive under the Income Tax Act 1967, allowing Malaysian companies to claim an allowance on qualifying capital expenditure (capex) when they invest in approved green technology assets.
The allowance is set off against a portion of the company's statutory income each year, reducing the amount of income subject to corporate tax. Any unused allowance carries forward to subsequent years until fully absorbed — there is no arbitrary cap on carry-forward.
GITA covers two asset tiers under the April 2024 MGTC Guidelines. The tier relevant to solar PV for own consumption is:
GITA Asset Tiers (MGTC Guidelines, April 2024)
| Tier | Qualifying Assets | GITA Rate | Set-Off Limit |
|---|---|---|---|
| Tier 1 | BESS (Battery Energy Storage System), EV charging infrastructure, Green Buildings, MOF-approved Tier 1 assets | 100% | 70% of statutory income / year |
| Tier 2 ★ Solar | Solar PV (own consumption), energy efficiency equipment (chillers, compressors, VRV/VAV), waste recycling systems, rainwater harvesting | 60% | 70% of statutory income / year |
Source: MGTC Green Technology Tax Incentive Guidelines — GITA Asset (REG NO. MGTC/DC/REC/GTGT-007, Revision 4, 24 April 2024). Solar PV for own consumption is classified under Tier 2 / Appendix 2. Note: BESS (Tier 1) qualifies for 100% allowance — a separate incentive that can be stacked with a solar installation.
Important clarification: Several older resources state "100% capital allowance" for solar. This referred to the previous scheme (pre-2024) or to BESS (Tier 1). Under the current April 2024 MGTC Guidelines, solar PV for own consumption is Tier 2 = 60% GITA. Always verify against the current MGTC Guidelines document (April 2024) or consult your tax agent.
2. GITA Worked Example: 240 kWp Commercial Solar System
How much can a company claim? A Malaysian company that buys solar PV for its own use can claim a GITA allowance of 60% of the qualifying capital expenditure. On a 240 kWp system at RM2,400 per kWp (RM576,000), that is RM345,600. It is set off against up to 70% of statutory income each year, and any unused allowance is carried forward until fully absorbed. At the standard 24% corporate rate, the tax saved once the allowance is fully used is RM82,944.
The figures below use Trexon's published commercial rate of RM2,400 per kWp and the GITA Asset rates in the MGTC 2024 Guidelines. The arithmetic is exact; what varies between companies is how quickly the allowance is absorbed, which depends on your statutory income. Your tax agent confirms the position for your accounts.
240 kWp commercial system at RM2,400/kWp
Capital expenditure
RM 576,000
240 kWp × RM2,400/kWp
GITA allowance (60%)
RM 345,600
Tier 2 — Renewable Energy System
Tax not paid (24%)
RM 82,944
Allowance × corporate rate
| Item | Value |
|---|---|
| Solar system capex (240 kWp × RM2,400) | RM 576,000 |
| 60% GITA allowance generated | RM 345,600 |
| Maximum set-off in any one year | 70% of that year's statutory income |
| Tax not paid — standard rate (24%) | RM 82,944 |
| Effective cost after GITA (24% rate) | RM 493,056 |
| Effective rate per kWp | RM 2,054 / kWp instead of RM 2,400 |
There is no fixed number of years over which GITA must be claimed. The only annual limit is the 70% statutory income cap, and any unused allowance carries forward until it is fully absorbed — a company with RM500,000 of statutory income absorbs this allowance in a single year, while one at RM100,000 takes five. A loss-making year defers the allowance rather than forfeiting it. Tax savings are in addition to the electricity the system displaces. An SME on the tiered rates (15% on the first RM150,000 of chargeable income, 17% up to RM600,000) saves less than the 24% figure. This example is arithmetic on published rates, not tax advice.
How long the allowance takes to absorb
| Annual statutory income | Set-off capacity (70%) | Years to absorb RM345,600 |
|---|---|---|
| RM 1,000,000 | RM 700,000 | 1 year |
| RM 500,000 | RM 350,000 | 1 year |
| RM 300,000 | RM 210,000 | 2 years |
| RM 200,000 | RM 140,000 | 3 years |
| RM 100,000 | RM 70,000 | 5 years |
Scaled by System Size (Illustrative)
GITA Savings by System Size — Illustrative
| System Size | Est. Capex | GITA (60%) | Tax saving at 24% (once fully absorbed) |
|---|---|---|---|
| 50 kWp (small factory) | RM 120,000 | RM 72,000 | RM 17,280 |
| 100 kWp (medium factory) | RM 240,000 | RM 144,000 | RM 34,560 |
| 240 kWp (large factory) | RM 576,000 | RM 345,600 | RM 82,944 |
| 400 kWp (large warehouse/plant) | RM 960,000 | RM 576,000 | RM 138,240 |
Capex uses Trexon’s published commercial rate of RM2,400 per kWp and the standard 24% corporate tax rate. Actual capex varies by roof type, location, and equipment spec. Use our GITA calculator for a project-specific estimate.
3. GITA vs GITE vs Normal Capital Allowance
Three different tax treatments are available for solar and green technology in Malaysia. Understanding which applies to your situation is critical before filing.
Tax Treatment Comparison
| Factor | GITA (Green) | GITE | Normal Capex Allowance |
|---|---|---|---|
| Who it is for | Companies buying solar for own use | Solar leasing / PPA operators | All companies — non-green assets |
| Benefit type | 60% of capex as tax allowance | 70% income tax exemption (up to 10 yrs) | Initial + annual allowance over the asset's life |
| Administered by | MGTC (solar own-consumption) | MIDA | LHDN (self-assessed) |
| Deadline | 31 Dec 2026 | 31 Dec 2026 | No deadline |
| Can you own the system? | Yes (required) | No — lessor owns it | Yes |
| Applies to ATAP/NEM export? | No — ATAP is a separate SEDA scheme for export credits | Separate; not the same as GITE Solar Leasing | N/A |
GITA and GITE are mutually exclusive for the same project. Source: MGTC Guidelines April 2024; MIDA GITE Solar Leasing scheme.
Key distinction from ATAP/NEM: GITA is a corporate tax incentive for the investment decision. Solar ATAP (Solar Accelerated Transition Action Programme) is a separate SEDA scheme that pays export credits when your solar panels send excess electricity to the grid. You can benefit from both simultaneously — GITA reduces your tax bill on the investment, while ATAP credits reduce your ongoing electricity bills. See our Solar ATAP 2026 guide for full ATAP details.
4. Who Qualifies for GITA (Eligibility Criteria)
The following criteria are drawn from the MGTC Green Technology Tax Incentive Guidelines (GITA Asset, April 2024). Your company must meet all of them:
Malaysian-incorporated company
Must be a new or existing company incorporated under the Companies Act 2016 and resident in Malaysia (Sdn Bhd or Bhd). Sole proprietorships, partnerships, and LLP structures do not qualify.
Asset used for own consumption — not income generation
The solar system must be installed on your business premises and used to reduce your own electricity consumption. A PPA arrangement (where another company owns the panels on your roof) does not qualify for your company.
New asset, owned by the company
The green technology asset must be new (not second-hand) and legally owned by the applying company.
Listed in MyHIJAU Directory (MGTC verification)
The qualifying asset must be approved by the Ministry of Finance, verified by MGTC, and listed under the MyHIJAU Directory. Listing attaches to the specific model installed, not to the brand or the installer, so confirm model codes before you order. We state the exact panel and inverter model codes in writing on the quotation so you can check them against the MyHIJAU Directory; final eligibility is subject to MGTC verification. We provide the itemised invoice and installation documents; the application is submitted to MGTC by your company or tax agent.
Capex incurred between 1 January 2024 and 31 December 2026
The qualifying capital expenditure must be incurred within this window. The application must also be submitted to MGTC within 24 months of the capex date (36 months for Green Buildings).
Application submitted after commissioning
MGTC requires the application to be submitted after the solar system has been commissioned and is operational. For renewable energy projects, you must have received the relevant energy generation licence/approval first.
A manufacturer claiming on its own plant can see how a system is sized and financed on factory and industrial solar installation; an office, hotel or retail owner should start with commercial solar installation in Malaysia.
5. GITA Application Process (Step by Step)
Commission your solar system
Ensure the system is fully installed, operational, and has received the relevant TNB approvals. For systems above 24 kWp, this includes the Solar ATAP connection agreement.
Obtain required documentation
Your installer provides: IEC-certified equipment specs (IEC 61215/61730 for modules, IEC 62109 for inverters), commissioning report (IEC 62446), electrical drawings (Professional Engineer endorsement only where required), and invoice/purchase evidence.
Submit MGTC GITA/A Form to MGTC
Send one set of the MGTC GITA/A Form with supporting documents to: Group Chief Executive Officer, Malaysian Green Technology and Climate Change Corporation, No. 2 Jalan 9/10, Persiaran Usahawan Seksyen 9, 43650 Bandar Baru Bangi, Selangor. Pay the processing fee (RM2,500–RM10,000 depending on capex value).
Receive MGTC verification letter
MGTC reviews the application and issues a verification letter confirming the asset qualifies. Do NOT submit any claim to LHDN (Inland Revenue Board / IRBM) before receiving this letter.
Claim via LHDN tax return
Your tax agent claims the GITA allowance in your annual income tax return (ITR). The 60% allowance is set off against up to 70% of statutory income each year. Unused allowance carries forward automatically.
6. GITA + Solar ATAP + Green Financing — The Full Stack
Savvy Malaysian manufacturers combine three incentives simultaneously to maximise the financial return on a commercial solar investment:
GITA
60% tax allowance
Reduces corporate tax liability on the capex. Claimed via MGTC + LHDN. Available until 31 Dec 2026.
Solar ATAP
Export bill credits
Surplus solar electricity exported to TNB earns credits on your electricity bill. Administered by SEDA. No Dec 2026 deadline.
Green Financing
Check current terms
GTFS 5.0 (Green Technology Financing Scheme, MGTC): a 60–80% government guarantee on the green-technology portion of a bank loan for companies; no interest rebate. Open until 31 Dec 2026 or until the RM1 billion allocation is used.
Combining them: a factory finances a 240 kWp system (RM 576,000) through a green technology loan, claims RM 345,600 in GITA allowance — worth RM 82,944 in tax at 24% once fully absorbed — and keeps the electricity the system displaces on top. The after-tax cost of the system falls well below the sticker price.
See our full solar financing options guide and GITA tax filing service for details on how Trexon handles the MGTC documentation end to end.
7. GITA Common Questions (FAQ)
When is the GITA deadline, and does it apply to the application as well?
Both. The MGTC Guidelines (April 2024) require qualifying capital expenditure to be incurred between 1 January 2024 and 31 December 2026, and the guideline applies to applications submitted to MGTC within that same window. Because the application can only be submitted after the system is commissioned, in practice the system must be installed, commissioned and the application lodged before 31 December 2026. Installation typically takes six to ten weeks, so decide as early as possible. A Budget 2027 announcement may extend the window; until it does, plan for 31 December 2026.
Does GITA apply if I use a PPA / SPPA (zero-capex model)?
No. Under a Power Purchase Agreement or Solar Power Purchase Agreement, the solar company owns the equipment and you pay for electricity consumed. Since your company does not incur the capital expenditure or own the asset, you cannot claim GITA. To qualify for GITA, you must purchase the system outright or via a hire-purchase / bank loan where you hold beneficial ownership.
Can I claim GITA and normal capital allowance on the same asset?
The GITA allowance and normal capital allowance cannot be claimed on the same capital expenditure for the same year of assessment. However, you can claim GITA on the portion qualifying as green tech, and Reinvestment Allowance or other allowances on different assets — subject to the conditions in the MGTC Guidelines (Section 5.1(g)). Your tax agent should review the interaction carefully.
What happens if my company does not have enough income to absorb the full GITA in Year 1?
The MGTC Guidelines explicitly state: "Unutilised allowances can be carried forward until they are fully absorbed." There is no 5-year hard cap on carry-forward; the limit is only on the annual set-off (70% of that year's statutory income). This makes GITA particularly valuable for companies with variable income, as the benefit is not lost — it simply defers to profitable years.
What is the MGTC processing fee?
Per the MGTC 2024 Guidelines: RM 2,500 for total asset cost under RM 500,000; RM 4,000 for RM 500,000–1,000,000; RM 7,000 for RM 1,000,001–5,000,000; RM 10,000 for above RM 5,000,000. This is a one-time government processing fee, separate from any professional fees charged by your tax agent or solar installer.
Does my solar installer need to be SEDA-registered?
The MGTC Guidelines require that the green technology asset be used in business carried out in Malaysia and that equipment meets IEC standards (IEC 61215/61730 for modules, IEC 62109 for inverters). In practice, all SEDA-registered installers (Registered PV Service Providers) supply IEC-certified equipment. Trexon Energy is a fully SEDA-registered RPVSP with complete MGTC documentation workflows.
8. Sources
- MGTC, Green Technology Tax Incentive Guidelines — GITA Asset (approved 23 April 2024): the 60% Tier 2 rate for renewable energy systems, the 70% statutory income set-off, the 1 January 2024 – 31 December 2026 capital expenditure window, and section 7, which applies the guideline to applications submitted to MGTC from 1 January 2024 until 31 December 2026.
- MIDA, GITA Project for own consumption merged with GITA Asset: administration moved to MGTC from 1 January 2024.
- LHDN, company tax rates: 24% standard; SMEs 15% and 17% on the first RM600,000 of chargeable income.
Budget 2027 is expected in October 2026 and may change these terms; this page will be updated when it does. Figures here are arithmetic on published rates, not tax advice.
Related Articles
GITA 60% Tax Allowance 2026: Dec 31 Deadline for Manufacturers
The urgency case: why the Dec 31 deadline matters and exact step-by-step timeline for factory owners.
Read moreCommercial Solar Cost Malaysia 2026
What drives the cost of factory and warehouse solar systems — roof type, inverter options and how a quote is built from your bills.
Read moreCommercial Solar Financing — Purchase, Loan, Hire Purchase + GITA
How to fund commercial solar by outright purchase, bank loan or hire purchase while still claiming the GITA allowance.
Read moreTrexon GITA Tax Filing Service
Outsourced MGTC documentation for your GITA Asset application.
Read moreGITA Tax Allowance Calculator
Enter your system size and tax rate to calculate your GITA allowance and net effective cost.
Read moreCommercial & Industrial Solar Solutions
Factory, warehouse, and office solar systems from a SEDA-registered installer.
Read moreSolar for Factory Malaysia
Rooftop solar for manufacturing plants, sized to your tariff and maximum demand.
Read moreIndustrial Solar Malaysia
Industrial solar panels and EPC delivery for large-load sites and industrial parks.
Read moreBESS Malaysia
Solar battery storage for peak shaving and maximum-demand reduction.
Read moreClaim Your 60% GITA Allowance Before the Deadline
Trexon prepares the documents you need for your MGTC application, including the commissioning report. Get a free quote with a GITA savings estimate for your facility.